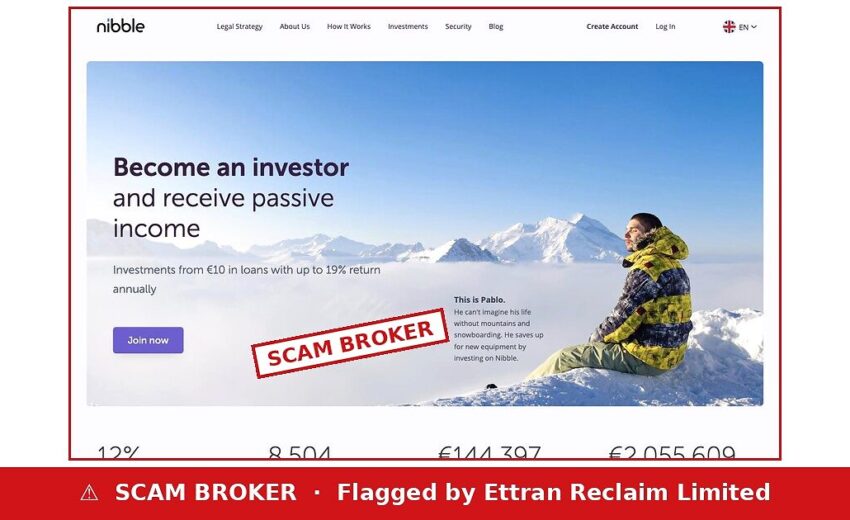
Nibble Finance leads with “Investments from €10 in loans with up to 19% return annually”. Scroll down and its own statistics block reports “12% Average product profit”. A strategy card says “12,5 % current annual interest rate”. Elsewhere it offers “14.5% premium interest rate insured with an 8% fixed return”.
| Brand | Nibble Finance |
| Domain | nibble.finance |
| Domain registered | 7 November 2019 |
| Product | Investment in consumer loans and overdue debt |
| Minimum | €10 |
| Returns advertised | 19% · 14.5% · 12.5% · 12% · 8% fixed |
| Own counters | 8,504 registered users · €144,397 paid to investors · €2,055,609 invested |
| Regulator action | CONSOB blackout order |
Five numbers is not a range
A headline rate of “up to” something is normal. Five different figures scattered across one site, none of them reconciled to the others, is not a range — it is a set of separate promises made to whoever happens to land on that page.
RELATED INVESTIGATION 👉
Timeline Investment Review: Unregulated Broker, Regulation Concerns
The gap matters most where it is widest. Somebody arriving at the homepage sees 19 per cent. Somebody reading the statistics sees 12. If the real figure is the lower one, the headline has done its job before the reader ever reaches the correction.
The counters do not flatter the platform
Nibble publishes its own totals: €2,055,609 invested and €144,397 paid to investors, across 8,504 registered users. Those are the platform’s figures, not ours, and they are the most useful thing on the site.
They describe a small operation. A platform holding two million euro is not an institution; it is a business that a single bad quarter can end. That is not an accusation — it is a size, and size is exactly what an investor needs to know before lending into consumer debt.
READ THIS BEFORE YOU INVEST 👉
Profit X Review: Fund-Safety Warning, Regulation Concerns
What is actually being sold
The product is investment in loans and “overdue debts”, including what the site calls the “Kazakhstan Premium Debt market”, with a non-performing-loan classification running “BB–B–CC”. Non-performing means the borrower has already stopped paying. Buying that debt at a discount is a real business, but it is a recovery business, and its returns depend on collection rates in a foreign legal system.
The word “insured” appears beside the 8 per cent figure. No insurer is named. An insurance claim with no insurer behind it is the single most load-bearing unverified word on any investment page.
TALK TO ETTRAN ABOUT A RECOVERY
Questions to ask before lending €10 or €10,000
Which of the advertised rates applies to the product you are actually buying, in writing. Who insures the “insured” tier, and what exactly is covered. What happens to your money if the platform stops trading. Which regulator supervises it, and in which country. And whether the recovery rates behind the returns have ever been audited by anyone outside the company.
What we verified
- Homepage headline reads “Investments from €10 in loans with up to 19% return annually” (read 25 September 2026).
- The same site’s statistics block states “12% Average product profit”.
- A strategy card states “12,5 % current annual interest rate”.
- The site also advertises “14.5% premium interest rate insured with an 8% fixed return” with no insurer named.
- Published counters read 8,504 registered users, €144,397 total paid to investors and €2,055,609 total invested.
- Product is described as investing in loans and overdue debts including the “Kazakhstan Premium Debt market”.
- Domain nibble.finance was created on 7 November 2019 according to RDAP registry data.
- CONSOB lists nibble.finance on its register of blackout orders.
Investing in consumer debt is a legitimate activity and a blackout order is an administrative measure rather than a finding of fraud. But five advertised returns on one website means at least four of them do not describe what you will be paid, and the site does not tell you which.